Homeowners insurance covers window replacement when something sudden broke the window: a windstorm, hail, a tree or limb coming down, a break-in, vandalism, or a fire. It does not cover a window that failed from age. Rot, a soft sill, a drafty single-pane window, and fog between the panes are all wear and tear, and every insurer treats wear and tear as the owner's cost.
That is the short version, and it is the same answer the big insurance sites give. What they skip is what matters for a Portland homeowner: how Oregon's own insurance regulator says a storm claim works, what a percentage deductible does to a one-window claim, and the fact that the most common window complaint here, foggy glass, is a manufacturer warranty item and not an insurance claim at all. We install Milgard windows in more than a hundred Portland-area homes a year, so below is the whole picture with our real prices next to it.
Storm damage or just old windows? Either way, start with a written price.
One visit, one written price with the exact Milgard series on every window, tear-out and haul-away listed. You can hand that estimate to your insurer, or use it to decide the claim is not worth filing.
OR CCB 198186 · WA L&I EXTERDC884PP · Family business since 2002
What is covered and what is not, cause by cause
Insurers call the covered events perils. A standard homeowners policy pays for window damage from a named or covered peril, up to the policy limit and minus the deductible. Everything that happens slowly is excluded. The table below is built from Progressive's and Grange's own coverage pages and the Oregon Division of Financial Regulation's storm guide.
| What broke the window | Homeowners insurance? | Who pays if not |
|---|---|---|
| Windstorm or hail | Usually covered | You, below the deductible |
| A tree or limb falls on the house, yours or a neighbor's | Usually covered, filed with your own insurer | You, below the deductible |
| Weight of ice and snow | Generally covered in Oregon | You, below the deductible |
| Break-in or vandalism | Usually covered | You, below the deductible |
| Fire | Usually covered | You, below the deductible |
| A ball through the glass | Often covered, or the other family's liability coverage | You, or the Milgard Full Lifetime upgrade if you bought it |
| Fog or moisture between the panes | Not covered: wear and tear | Milgard warranty, 20 years for the original owner |
| Rot, a soft sill, peeling frames | Not covered: wear and tear or neglect | You |
| Drafts, single pane, high heating bills | Not covered: age | You, with rebates where they apply |
| A stress crack in the first year | Not covered | Milgard warranty, 1 year |
Two things in that table trip people up. First, a neighbor's tree is still your claim. Oregon's regulator puts it plainly: even if the tree is rooted in the neighbor's yard, you submit the claim to your own insurance company, and your insurer decides whether the neighbor bears any responsibility. Second, a home warranty is not homeowners insurance. Progressive notes that a home warranty typically does not cover windows and doors at all.
What Oregon's insurance regulator says about storm claims
The Oregon Division of Financial Regulation runs a storm page for homeowners, and it answers the questions people ask us after a bad night of wind. The points that apply to windows:
- Falling trees and limbs: if a tree falls on the house, the damage may be covered, and the policy generally pays to remove the debris when the tree caused damage. A tree that falls in the yard and hits nothing is usually not covered for removal.
- Ice and snow: homeowners policies generally cover damage to the house from the weight of ice and snow. That is the kind of storm Portland gets, like the January 2024 ice storm that brought down trees and limbs across the metro area.
- Deductibles: many Oregon policies carry a percentage deductible instead of a flat one. The regulator's own example is a 0.5 percent deductible on a $300,000 dwelling limit, which works out to $1,500 before the insurer pays anything.
- Whether to file: the regulator says the damage can be less than or close to the deductible, so weigh the cost and benefit before filing. A reported claim can affect your future premium or your ability to get coverage.
- Temporary fixes: save every receipt for temporary repairs such as boarding up an opening. Those costs are part of the claim.
- Help: the division's consumer advocates take questions for free at 888-877-4894.
Foggy glass is a warranty item, not an insurance claim
A lot of window calls are not about a broken window. They are about a window that fogged up between the two panes. That is a failed seal on the insulated glass unit, and no insurer covers it, because it is wear and tear. It is a manufacturer warranty item, and the terms changed on November 1, 2026.
Under Milgard's current Replacement Product Lifetime Limited Warranty, the original owner who lives in the home gets 20 years of coverage on the insulated glass unit for fog, dust or moisture between the panes, lifetime coverage on the frame, and one year on a stress crack. Any later owner gets 10 years from the manufacture date. Plain glass breakage is not covered under the standard warranty. Milgard also lists acts of nature, vandalism, and caulking as outside the warranty, so a storm-broken window is an insurance question, and the caulk line around the window is maintenance.
Milgard's optional Full Lifetime Warranty upgrade, which has to be bought on the sales order for the V300, V400 and C700 series, adds coverage for non-specialty broken or cracked glass during the original owner's ownership. It still excludes breakage from acts of nature such as fire or earthquake, and from vandalism. So the ball through the glass can be a warranty claim if you bought the upgrade, but the tree through the glass is still your insurer's.
Our own workmanship warranty covers the install side, up to a limited lifetime on installs when the estimate says so, and 5 years on the rest. The full terms are on our window and fence warranty page.
Is one broken window worth a claim? The deductible math
Grange's advice is the honest one: if your out-of-pocket cost to replace the window is only slightly more than your deductible, pay it outright instead of filing. Progressive says the same thing a different way: get a repair estimate first to see whether the cost may exceed the deductible. Here is what that looks like with our installed prices, which include tear-out and haul-away of the old window.
| Windows damaged | Installed cost, Milgard V250 or V300 | Against a $1,500 deductible |
|---|---|---|
| 1 window | $1,200 to $3,300 | At or near the deductible: usually not worth a claim |
| 2 windows | $2,400 to $6,600 | Borderline: file if the damage is on the high side |
| 3 or more windows, a limb through the wall | $3,600 and up, plus siding or framing | File the claim |
The V250 Style Line runs $1,200 to $3,000 installed and the V300 Trinsic $1,300 to $3,300. Those two series are the ones we install most. A single broken window in a Portland home almost always lands inside the deductible on a percentage policy, which is why every window job we have done so far was paid by the homeowner, not an insurer. A tree across the front of the house is a different story, and that claim is worth filing even with the premium risk.
Every price above comes from our Portland window replacement cost guide, which breaks down what moves the number for each series.
How a storm claim works when we do the replacement
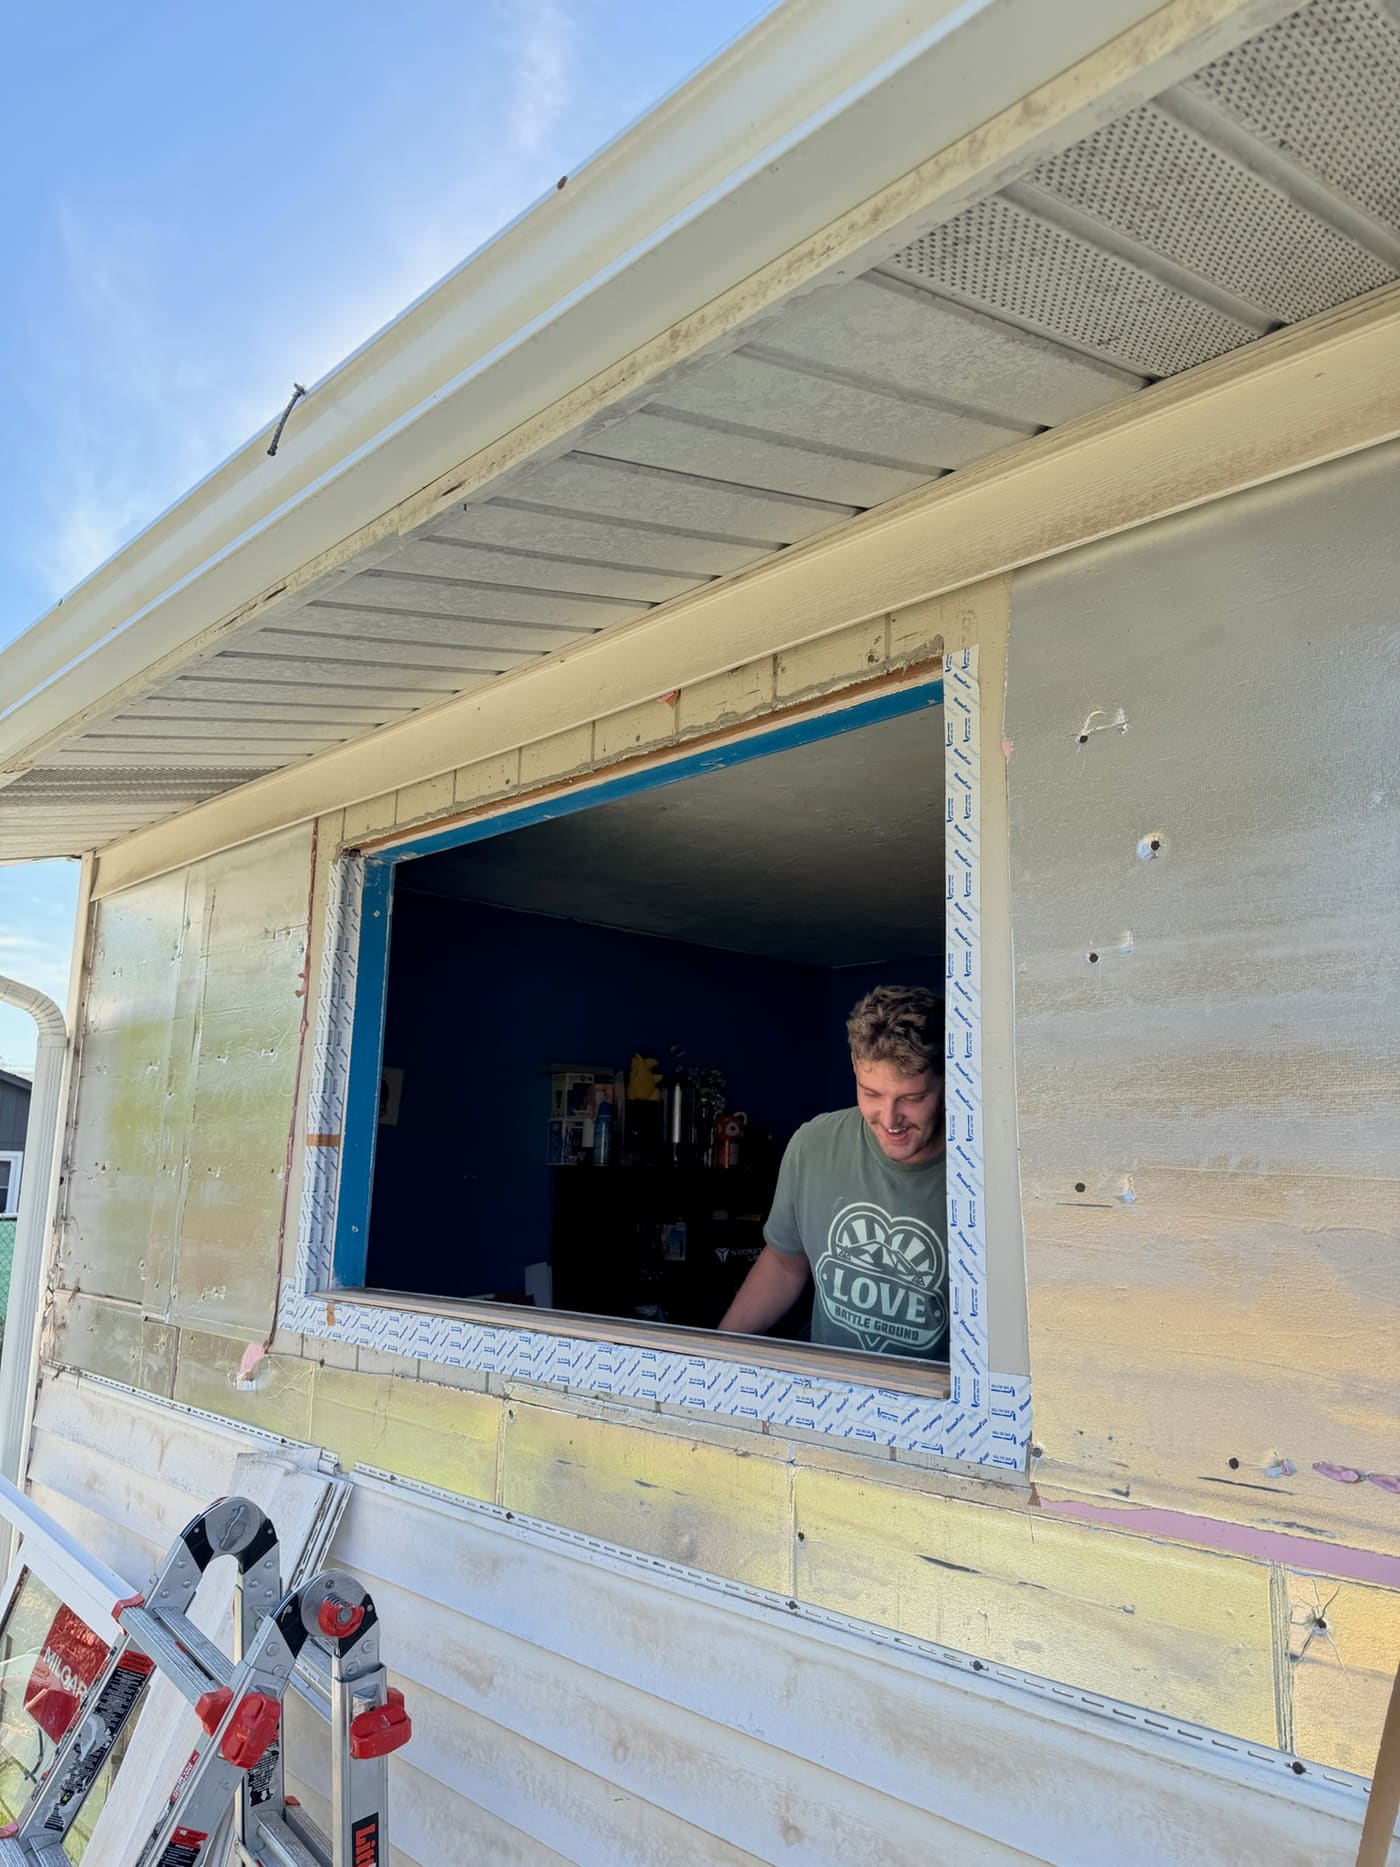
We are the installer, not the adjuster. The homeowner is our customer and deals with the insurer. Here is the order that keeps a claim simple:
- Make it safe and take photos before you touch anything. Progressive's advice is photos first, then have a qualified professional look at the window. Pictures of the tree still on the house are worth more than pictures of the cleanup.
- Cover the opening and keep the receipts. Plywood, plastic and tape are temporary repairs the policy can pay back.
- Call your insurer, not the neighbor's, and ask about your deductible before you decide to file.
- Get a written estimate. We measure every opening on one visit and leave one written price with the exact Milgard series on each window. That is the document the insurer wants, and it is also what tells you whether the claim clears the deductible.
- Expect like-for-like, minus the deductible. The insurer pays to put back what you had. Oregon's residential code still holds the replacement window to a U-factor of 0.27 or lower, so the new window is a step up from the old one whether the insurer meant it or not.
- Plan for the lead time. Windows take 3 to 4 weeks from measure to install, so the temporary cover stays up for about a month. Bedrooms also have to meet Portland's egress rule for the escape opening, which can change the style we can put back in.
Most Portland window jobs are full-frame tear-outs, about 8 in 10 of ours, because the homes we work in were built anywhere from 1942 to 2002 and the old frames are rarely worth keeping. That is true for a storm replacement too. If the tree bent the frame, there is nothing to set a new sash into, and a full-frame window with new flashing is the right fix.
One more thing homeowners and insurers ask about after a storm: the contractor's own coverage. Gorilla Works is licensed in Oregon (CCB #198186) and registered in Washington, and carries $1,000,000 in general liability insurance. A certificate of insurance is available on request, which matters when an insurer is paying part of the bill.
Glass only, or the whole window?
Glass does not get repaired. A cracked or broken pane gets replaced, either as a new sealed glass unit in a frame that is still sound, or as a whole new window when the frame is old, bent or rotted. We do full window replacements, not repair work, so the price we give you is for the complete window with tear-out and haul-away. For a glass-only swap on a newer window that is still under its manufacturer warranty, the warranty line is the first call: Milgard's is 1-800-645-4273, and claims have to be filed within 30 days of finding the problem.
Not sure whether the window should be saved? Our guide on when to replace windows in Portland covers the signs that mean the frame is done.
The Portland side of this
The older neighborhoods with the biggest street trees, like Laurelhurst, Eastmoreland and Irvington, are also the ones with the oldest windows. When an ice storm takes a limb down into a 1950s picture window, the insurer pays for the picture window. The other nine windows on the house, which are the same age, are still the owner's project. Many homeowners use the claim as the moment to replace the rest, and the financing works the same: payment plans with zero down are available for qualified homeowners. All financing is subject to credit approval. Rates, terms and payments may vary based on credit.
If you are replacing everything, start with the types of replacement windows guide to pick a style for each room, then book the measure.
Need an estimate for the insurer, or for yourself?
We quote one window or the whole house, no minimum. One written price, the exact Milgard series on each line, and a 3 to 4 week install date.
OR CCB 198186 · WA L&I EXTERDC884PP · Family business since 2002
Frequently asked questions
Does homeowners insurance cover window replacement due to age?
No. Windows that are old, drafty, rotted or fogged are wear and tear, and standard homeowners policies exclude wear and tear. Replacing them is a home improvement, and the cost is yours. Energy rebates and financing can bring the number down, but insurance will not.
Does homeowners insurance cover window seal failure?
No. Fog or moisture between the panes is a failed seal, which insurers treat as wear and tear. It is a manufacturer warranty item instead. Milgard covers the insulated glass unit for 20 years for the original owner-occupant and 10 years for any later owner, counted from the manufacture date.
Does insurance cover broken windows from a break-in?
Usually yes. Theft and vandalism are covered perils on a standard policy, so the broken window, the damaged frame and the door that was forced are all part of the claim, minus your deductible. A police report helps the claim.
Will one window claim raise my premium?
It can. The Oregon Division of Financial Regulation warns that a reported claim could affect your future premium or your ability to get coverage. That is why both the regulator and the insurers say to compare the damage to the deductible before filing. One window is rarely worth it; a limb through the wall is.
My neighbor's tree broke my window. Whose insurance pays?
Yours. Oregon's regulator says to file with your own insurer even when the tree was rooted next door. Your insurer then looks at whether the neighbor was negligent, for example by ignoring a tree that was clearly dead. A healthy tree that came down in a windstorm is treated as an act of nature, and your own policy handles it.
Does insurance pay for better windows than I had?
The policy pays to replace what you had, up to your coverage limit and minus the deductible. In Oregon the replacement still has to meet the current residential energy code, a U-factor of 0.27 or lower, so the new window is a step up regardless. If you want to move from a basic series to a fiberglass C700, the difference is yours.
Sources
- Oregon Division of Financial Regulation, Storm damage and homeowners insurance (wind, falling trees, ice and snow, percentage deductible example, filing advice, consumer advocate line)
- Progressive, Does homeowners insurance cover broken windows? (updated October 30, 2025)
- Grange Insurance, Does homeowners insurance cover windows?
- Milgard, Replacement Product Lifetime Limited Warranty and 10-Year Limited Warranty for all other owners (effective November 1, 2026)
- Milgard, Full Lifetime Warranty Upgrade (effective November 1, 2026)
- OPB, Recent storms wreaked havoc across Oregon: navigating insurance claims (January 19, 2024)
- Oregon Residential Specialty Code 2023, Chapter 3 Building Planning (emergency escape openings)
- Oregon Residential Specialty Code 2023, Chapter 11 Energy Efficiency (fenestration U-factor)
- Gorilla Works, Portland window replacement cost guide (installed price ranges by Milgard series)
Gorilla Works proudly serves Portland, Gresham, Beaverton, Hillsboro, Tigard, Lake Oswego, Happy Valley, Milwaukie, Troutdale, Vancouver WA, and Camas WA. Call (971) 343-4964 or request window installation.